You planned the month—so why are you short?
The month starts with that clean feeling: bills listed, groceries estimated, savings line set. Then the balance drops faster than it “should,” and it’s hard to point to a single bad decision. Nothing looks reckless, so the mind goes to bigger explanations—prices, bad luck, a surprise expense—but the leak is usually smaller and more ordinary.
Most times, the plan wasn’t wrong on paper; it was incomplete in real life. A few purchases land in the wrong place, a couple of costs arrive earlier than expected, and some spending never gets tracked with the same seriousness as rent. By the time you notice you’re short, the month has already made the trade-offs for you.
When payday timing quietly breaks your plan
It often starts with a calendar mismatch, not a spending problem. The budget assumes a “monthly” rhythm, but your paychecks don’t always behave that way. If rent and childcare come out on the 1st and 3rd, but you get paid on the 5th and 20th, the first half of the month has to float on whatever cash is left from last month. That’s where the plan quietly breaks—timing forces short-term borrowing from a credit card, a buffer account, or the next paycheck.
The friction is subtle because totals still look fine. On paper you can afford everything, yet cash flow says otherwise. Late fees, overdrafts, and small “bridge” purchases show up, and then the second paycheck feels smaller because it’s already assigned to covering the gap. A quick fix is to plan in pay periods: list what must be paid before the next payday and fund that first, even if it means delaying an extra savings transfer by a week.
Categories that look right but hide real spending
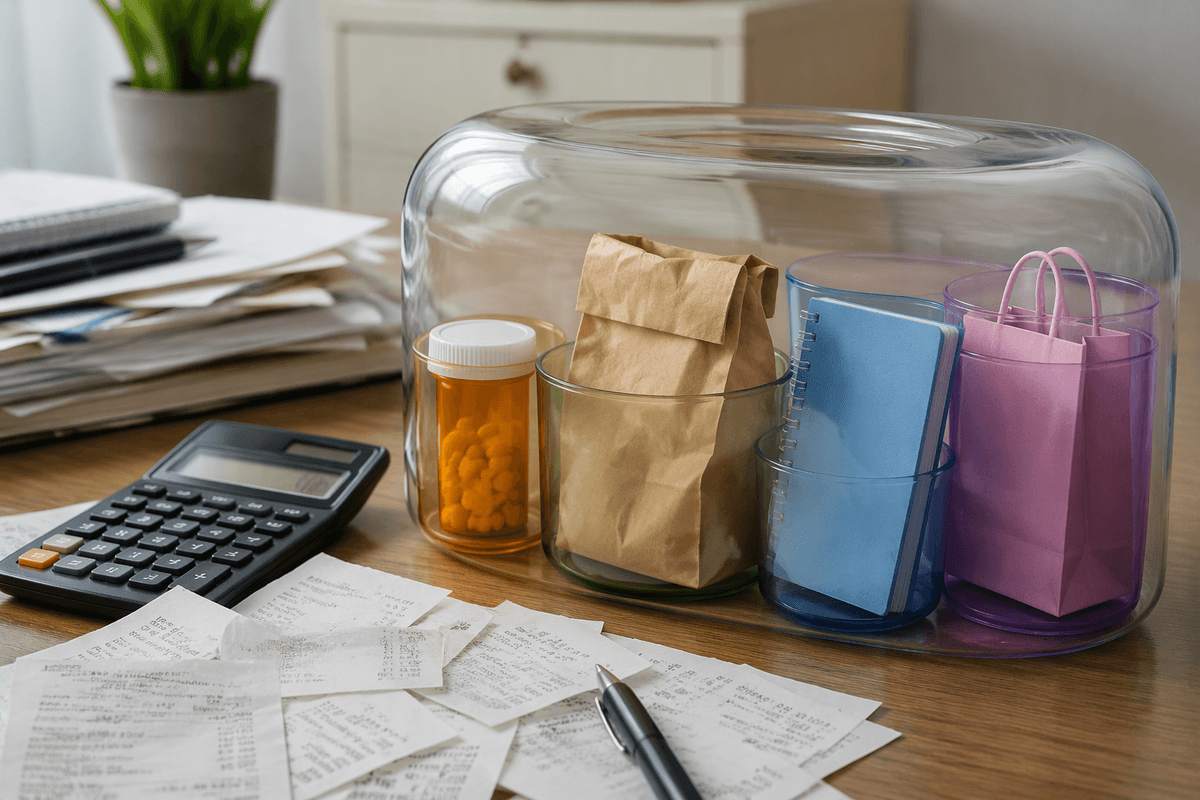
Even after you switch to pay-period planning, the numbers can still “work” and the cash can still disappear. That’s usually when categories start doing a little lying. Not because you picked the wrong amounts, but because the spending is getting parked in places that feel harmless—“household,” “misc,” “kids,” “work stuff.” The totals look tidy, but the category is acting like a junk drawer, and it keeps you from noticing that a few small patterns are now expensive.
The constraint is time: in a busy week, you’ll code a $38 pharmacy run as “groceries” just to move on, or you’ll split nothing and let takeout, school fees, and a quick Target stop blur together. By the third repeat, it’s no longer an exception; it’s the real budget. For one month, tighten three categories with simple rules (no “misc” over $25, split mixed receipts, separate eating out), then watch which line item grows when the fog lifts.
Subscriptions: the spending you stop noticing
A few weeks into cleaning up categories, there’s usually an uncomfortable moment: the “fixed” bills are higher than you remembered. Not the big ones—those are already on the list—but the quiet stack of subscriptions that never trigger a decision. They don’t feel like spending because nothing is happening at checkout. They just land, on different days, under different names, and your brain files them as background noise.
The constraint is that canceling takes time and attention you don’t have on a Tuesday night, so the default is to let them ride. Streaming plus add-ons, extra cloud storage, an old fitness app, a kids’ learning tool, a delivery membership—each one is “only” $7–$19 until three of them renew in the same week you’re trying to stay inside the grocery number.
For one month, pull a subscription list straight from your bank and card statements and give every line one of three labels: weekly use, seasonal, or forgotten. Pause the seasonal ones (set a calendar reminder to restart), cancel the forgotten ones, and move what remains into a single “Subscriptions” category with a hard cap so it competes honestly with savings.
Irregular bills that aren’t emergencies anymore
After subscriptions are finally in one place, the next punch usually comes from bills that are “rare” only in your memory. The car registration hits, a school fundraiser envelope comes home, the annual deductible resets, the HVAC needs service, the water bill jumps because it’s the quarter you pay trash too. None of it is a true surprise anymore, but it still gets treated like one because it doesn’t show up every month.
The constraint is timing and legitimacy: you can’t negotiate the due date, and ignoring it costs more. So it gets paid from groceries, savings, or the credit card, and the budget looks “blown” even though you did the responsible thing. The fix isn’t guessing better—it’s admitting the bill exists before it arrives.
Pick three recurring irregulars you can name without looking (car, medical, school). Find the annual total from last year’s statements, divide by 12, and auto-move that amount into a separate “Irregular bills” bucket each payday. When the bill lands, you pay it like rent—calmly, from money that was already waiting.
One-off purchases that become a new baseline
The irregular-bills bucket takes the panic out of “known unknowns,” but the budget can still get bent by purchases that arrive as a single, reasonable decision. A new set of tires, a phone replacement, a patio chair that finally fixes the broken one—none of it feels like lifestyle creep. The constraint is usually timing: it lands on a month that already has registration, a birthday, and a heavier grocery week, so it gets pushed onto the card “just this once.”
The part that changes your cash flow is what happens after. The tires create a new expectation for maintenance. The new phone triggers a higher case, higher insurance, maybe a new plan. The patio chair quietly turns into “we should finish the set.” When a one-off adds even $25–$60 of ongoing monthly spending, treat it like a new bill: write the follow-on costs into categories that match, and cut something else on purpose that same week.
Skipping check-ins until the month is over
After a one-off turns into a new baseline, the easiest move is to avoid looking too closely until the month closes. It’s not laziness; it’s the fear of finding out you’re already “behind” with two weeks left. The constraint is timing: once the big bills clear, the rest of the month fills with small, fast decisions, and the budget app becomes a history book instead of a steering wheel.
When the first real check-in happens on the 28th, there’s nothing left to adjust. Groceries ran hot, dining out blurred into “busy nights,” and the irregular-bills bucket got tapped “temporarily.” Then savings is the only flexible line, so it gets quietly reduced without a clear choice being made.
A tighter habit is a 10-minute mid-month reset tied to a real date (the 10th and the 20th, or the day after each payday). Pick one question: “What has to be true by next payday?” Then freeze one category, trim one, and move money once—while it can still change the ending.
Turn the six mistakes into one simple routine
Once the check-ins are on the calendar, the rest can stop being six separate “things to remember” and become one repeatable pass. The constraint is attention: you only have a few minutes, and you need it to work even when the week is messy.
Right after payday (or the day after), do the same four steps: (1) fund “before next payday” bills first, (2) sweep subscriptions into one capped line, (3) move the preset amount into the irregular-bills bucket, then (4) skim the last seven days for category drift—anything coded as “misc/household” over $25 gets re-labeled. If a one-off showed up, you decide the trade-off immediately: which category gets cut this week so it doesn’t silently become the new baseline.
By the second cycle, the budget starts acting less like a promise and more like a set of guardrails that updates with real life.